Zero-water cooling mandates could leave America thirstier
- Post Date
- 30 September 2026
- Read Time
- 10 minutes
In 2025 and 2026, US lawmakers introduced more than 60 bills targeting data center water use. At least 12 states have considered requiring new facilities to use “closed-loop” cooling. The instinct is understandable: seven in 10 Americans say they would oppose a data center in their area, with water among their top concerns. But the policies now being written risk addressing a simpler, more visible problem while ignoring a more pressing one, and missing a once-in-a-generation opportunity to leave communities with better water infrastructure than before the demand for AI emerged.
Closed-loop and its many definitions
Definitions of closed-loop cooling in legislation vary from state to state. South Carolina’s HB 4583 focuses on net-zero water withdrawal and wastewater discharge, while barring the use of groundwater or municipal water for cooling. Kansas’s SB 400 defined closed-loop as a sealed system with no fluid-to-atmosphere contact. Illinois’s POWER Act sets an efficiency benchmark rather than a technology mandate, and in Michigan, legislators have considered requiring closed-loop cooling or limiting facilities to water supplied through municipal systems.
The engineering reality is equally complex. Many closed-loop liquid-cooling systems, such as direct-to-chip, keep coolants sealed around AI chips, but that heat must still be removed from the building through dry coolers, mechanical chillers, or evaporative cooling towers. Data center operators often cite the sealed liquid loop as a closed-loop system because, once filled, it can operate for years with little or no additional water. However, a facility’s overall water footprint largely depends on how heat is removed. A mandate that does not distinguish between cooling systems and local conditions risks regulating terminology rather than watershed outcomes.
Meanwhile, public attention is accelerating, and policy is moving faster than the shared vocabulary needed to write it well.
A rare chance to build lasting public infrastructure
Most US water utilities are small, not-for-profit systems managing historically underfunded assets. Data center growth is projected to require between $10 billion and $58 billion in new water infrastructure nationwide, largely because peak summer water use can be six to ten times higher than a facility’s average draw.
It’s a burden but also leverage. Data center developers are among the few private customers who are both able and willing to fund utility-scale assets up front. Across the examples below, operators have committed more than $796 million to water-related infrastructure in six states. These are in addition to Meta’s $1 billion-plus pledge for infrastructure around its Louisiana campus and Amazon’s more than $1 billion commitment to recycled water infrastructure.
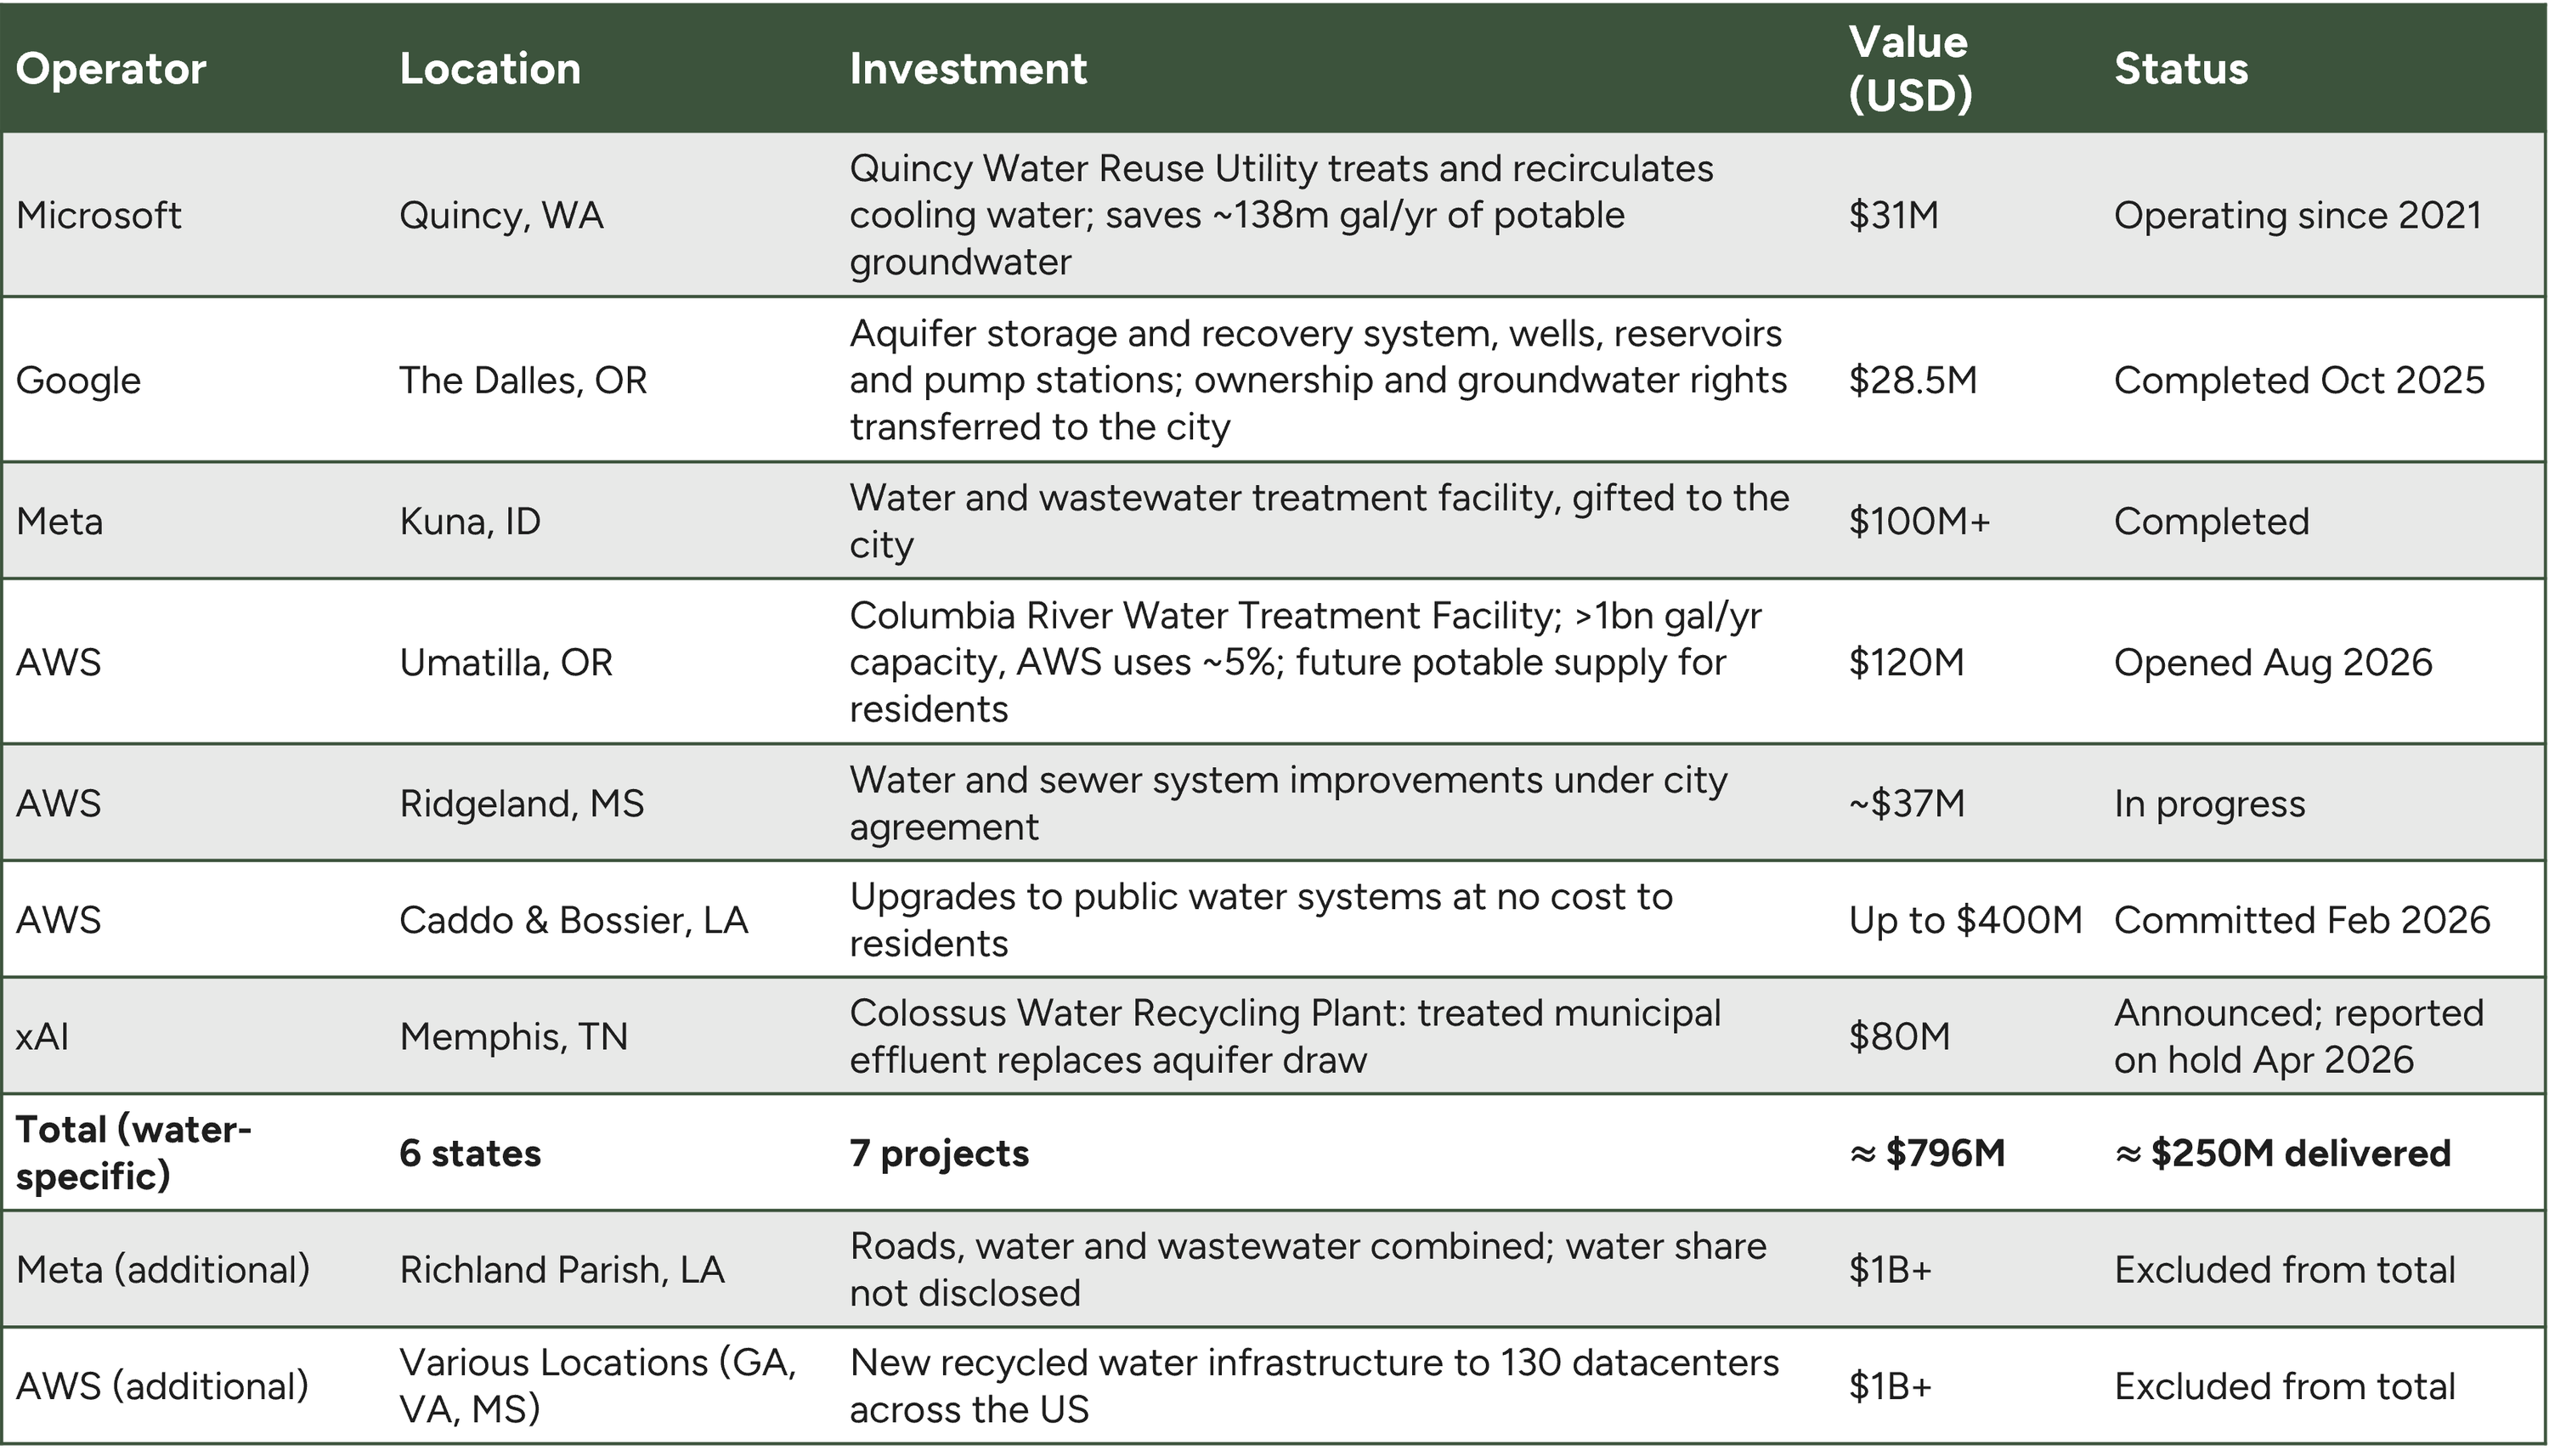
The strongest of these deals shares a pattern. Rather than simply paying connection fees, the operator funds an asset that the community owns, and that outlasts the data center’s own needs. In Umatilla, Oregon, AWS expects to use about 5% of the new treatment plant’s capacity, with the rest serving current industrial needs and future drinking water needs. A similar approach can be seen in Kuna, Idaho, where Meta funded a new water and wastewater facility, which was later transferred to city ownership. These examples show that lasting public value depends on community ownership, enforceable milestones and clear accountability for delivery. For regulators and utilities negotiating with developers, we’re starting to see what good practice looks like:
- Water infrastructure and associated water rights are transferred to public ownership where possible.
- Capacity sized for regional growth, not just data center demand.
- Intention to keep water/wastewater rates affordable for residents.
- Use reclaimed, non-potable or effluent sources for cooling where quality and regulation allow.
- Include enforceable milestones, cost-recovery provisions and rate protections in development agreements.
- Require developers to help fund any power grid upgrades needed to support their facilities.
When saving water on-site costs water elsewhere
Evaporative cooling is widely used for a reason; it saves energy. Industry disclosures suggest water-cooled data centers can use 25–35% less electricity than air-cooled ones during peak summer periods. In Nevada, a facility relying on non-evaporative cooling showed an annual PUE (Power Usage Effectiveness) 6.4–10.2% higher than a sister site from the same operator that relies on evaporative cooling. Power generation is thirsty. According to Lawrence Berkeley National Laboratory, indirect water consumption associated with electricity is about 12 times the direct cooling water used by US data centers.
Consider a 100 MW IT load running year-round. If a switch to dry cooling in a warm region with mechanical chillers raises PUE from 1.20 to 1.32, consistent with the Nevada comparison, annual electricity consumption would increase by approximately 105 GWh. Based on the average US grid water consumption of 3.1 litres per kWh, the extra power would require around 86–103 million gallons of water at power plants.
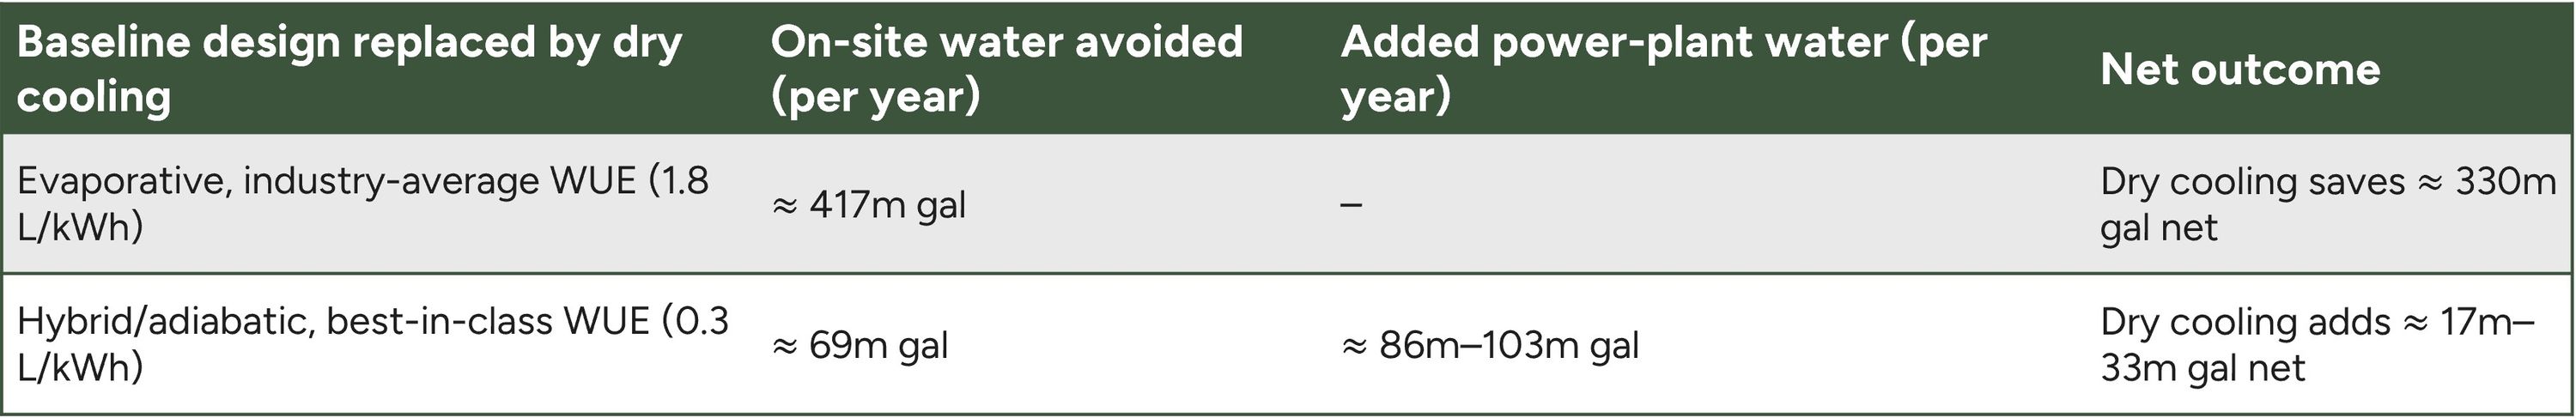
Compared with older evaporative designs, dry-cooling mandates still save water overall. But against today’s best hybrid and adiabatic designs, the same mandate can increase total water consumption by requiring more electricity. That extra power demand often occurs on the hottest afternoons, when grids are most stressed and least efficient plants are running.
This is no longer a fringe view. Southern Nevada has barred evaporative cooling in new commercial construction since 2024, while industry discussions have increasingly focused on the trade-offs associated with mandated alternatives. The caveat is geography: power-plant water may be drawn from a different, less-stressed basin than the one where the data center is located. That is precisely why a consistent method for measuring water impacts is needed.
The US needs a standard for Scope 2 water
Carbon accounting settled a similar challenge years ago. The GHG Protocol’s Scope 2 guidance gives companies a common way to account for emissions from purchased electricity. Water has no equivalent. While the Green Grid defined a source-energy version of WUE (Water Usage Effectiveness) in 2011, it remains voluntary and is rarely used and reported. The EU’s Energy Efficiency Directive only measures on-site WUE, and California’s AB 2619 would be among the first US laws to require reporting of indirect water use; however, it doesn’t contain a nationally defined and adopted method.
There is still debate about whether off-site water should be included in a data center’s footprint, with some researchers arguing that it isn’t counted in other industries. That debate highlights a good case for a consistent standard.
A credible US framework should:
- Use published, regional water-consumption intensity factors for electricity (for example, by balancing authority) by eGrid, updated annually.
- Report consumption and withdrawal separately, and flag basins and water-stress level where each occurs.
- Capture seasonal or hourly variation, so that peak-period trade-offs are visible.
- Require cooling mandates to be tested against total (Scope 1 and Scope 2) water per unit of IT energy under local climate conditions.
- Set clear rules for market-based claims tied to contracted low-water generation, such as wind and solar.
Federal agencies, standards bodies, and state regulators all have a role, but the objective should be the same: judge cooling design by its total water outcome, not by what happens inside the fence line. The ongoing debate about the true impact of data centers on natural resources should be addressed through robust data and reporting. With the ability to gather data in remote areas and compile it in centralized systems, the very industry creating such a stir in our backyards is uniquely suited to help find the answer.
Getting the next decade right
The data center build-out will shape US water and power systems for decades. When written well, the rules can deliver resilient public infrastructure and genuinely reduce water use. For example, allowing the use of reclaimed water from wastewater treatment plants can reduce demand for freshwater, leaving more water available for critical community needs such as public health and future economic growth.
Written in haste, however, rules risk creating more debate than solutions and could discourage private investment in public water infrastructure. Yet data center companies are already incentivized to reduce waste in their operations, both to lower costs and to meet growing customer expectations for efficiency. As demand for AI continues to grow, pressure to operate more efficiently will only increase. The goal should be to encourage that innovation while continuing to hold the industry accountable for delivering measurable public benefits.
As the sector grows, the real opportunity is not just to use less water on-site, but to make decisions that reduce overall environmental impact and leave communities with stronger infrastructure.
SLR’s water advisory team helps developers, utilities, and regulators assess water and energy trade-offs, protect stressed water resources, and design practical solutions that create lasting public value. To learn more about how we can support responsible data center growth, contact Beau Schilz.
This article is part of a wider series of Insights that share SLR's perspectives, expertise and experience across the evolving data centre and digital infrastructure landscape. Explore related insights below:
- Sustainable AI Mitigating Water Risks in the Data Centre Boom
- Data Centre Cooling in Australia
- Energy Solutions for Data Centres
- The sustainability challenges shaping the digital future landscape
- What you should know about the new US federal action on data centers
- Powering the digital age: the critical role of resilient data centres
- Challenges to reach net-zero data centres
References
- MultiState – state data centre water legislation (Mar 2026), MultiState – Michigan legislation; 12 states considering closed-loop (Jul 2026)
- Schneider Electric – 60+ bills; state definitions (Aug 2026)
- Shaw Local – Illinois POWER Act (Jul 2026)
- DLA Piper – California AB 2619 (May 2026)
- E&E News – Gallup poll; Florida law (May 2026, E&E News – utility structure and IIJA expiry (Apr 2026)
- CU Boulder – Thirst for Data report (Jul 2026)
- CRS – Data Centers and Water FAQ (Jul 2026)
- MSW Magazine – $10bn–$58bn infrastructure need (2026)
- US EPA – Quincy water reuse case study
- Microsoft – Quincy $31m contribution
- OPB – Google The Dalles $28.5m (Jan 2026)
- Google – The Dalles ASR completion (Oct 2025)
- Meta – Kuna and Richland water stewardship, Meta – Richland Parish $1bn+ infrastructure (Jul 2026)
- Hermiston Herald – Umatilla $120m plant (Aug 2026)
- WLBT – AWS Ridgeland $37m (May 2026)
- Amazon – Louisiana up to $400m water infrastructure
- Action News 5 – xAI Memphis $80m plant (Oct 2025)
- WREG – xAI plant on hold (Apr 2026)
- Ren et al. – Small Bottle, Big Pipe (preprint, 2026)
- ITIF – LBNL indirect water ≈12× direct (Jul 2026)
- Li et al. – Making AI Less Thirsty (3.1 L/kWh; Meta 3.7 L/kWh)
- The Green Grid – WUE White Paper #35 (2011)
- Undark – Koomey counterpoint on indirect water (Dec 2025)
Recent posts
-
-
-
The economics of mine closure and what comes next
by Dr. Chris Meikle, Jeremy Collyard, Elysśa De Carli
View post